


To prepare a P&L and balance sheet, close the books first: record every transaction, reconcile bank and card accounts, run a trial balance and post adjusting entries. Then prepare the P&L (revenue minus cost of goods sold and operating expenses, down to net income), carry net income into retained earnings, and build the balance sheet so assets equal liabilities plus equity. The cash flow statement comes last and explains why cash moved differently from profit.
This guide walks through that order step by step, with what goes on each line of the P&L and the balance sheet, a worked example for a consumer brand, and the checks that catch errors before anyone else does. If you would rather have the monthly close and the statements done for you, our financial reporting services team prepares all three statements for growing businesses.
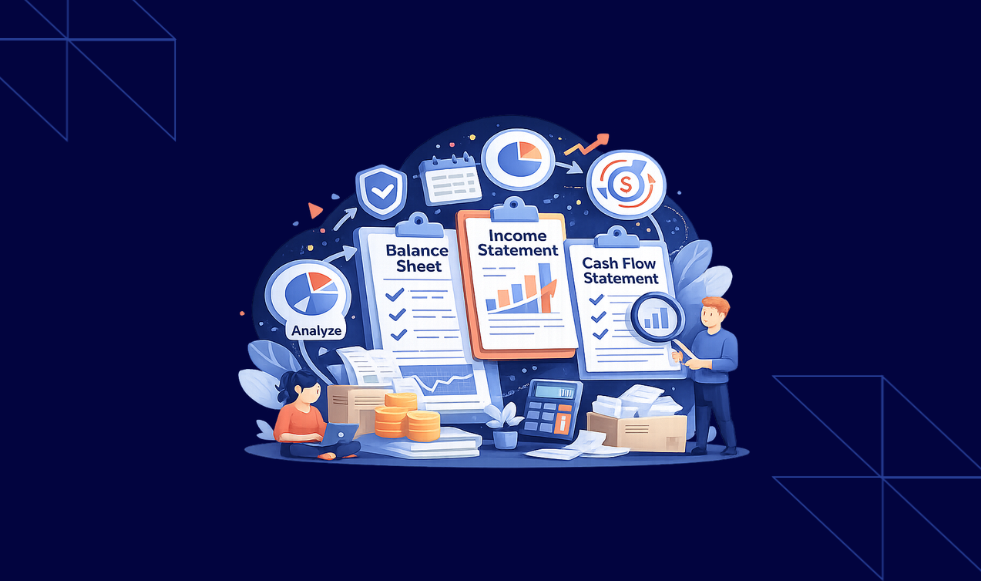
The three statements, and the order to prepare them
Most businesses prepare three core financial statements. The US Securities and Exchange Commission’s beginners’ guide to financial statements describes them this way (it adds a fourth, the statement of shareholders’ equity, which larger companies also publish):
| Statement | What it shows | Period |
|---|---|---|
| Profit and loss (income statement) | Revenue earned and expenses incurred, down to net profit or loss | A month, quarter or year |
| Balance sheet | What the business owns and owes, and what is left for the owners | A single date |
| Cash flow statement | Where cash came from and where it went | A month, quarter or year |
They are prepared in that order because each one feeds the next. Net income from the P&L becomes part of retained earnings on the balance sheet. The cash flow statement then starts from net income and uses the changes between two balance sheets to explain the movement in cash. Prepare them out of order and the balance sheet will not balance.
Why Financial Statement Preparation Matters
Financial statements are more than compliance documents. They tell you what you own, what you owe, how much you earn and how much cash you really have. They matter in three places.
Strategic Decision-Making
Pricing, hiring, inventory buys and funding all depend on knowing your margins and your cash position. A founder who reads the P&L by product line can see which products carry the business and which only add revenue.
Operational Efficiency
Gross margin, operating expenses as a share of revenue, and inventory turnover show where money leaks. Tracked monthly, they point back to the operational cause: a supplier price rise, a shipping rate change or a marketing channel that stopped paying back.
Investor and Lender Confidence
Banks and investors read the balance sheet and cash flow statement before they lend or invest. Clean, reconciled statements delivered on time are the first sign that the numbers can be trusted. Untidy books are the first red flag.
Before the statements: close the books
The statements are only as good as the records behind them. Every month, the close follows the same steps.

- Collect and organize the records. Sales invoices and platform payout reports, purchase bills, expense receipts, payroll records, bank, card and loan statements, and tax records. For an online brand, that includes Shopify, Amazon and payment processor reports, which often net fees and refunds out of the deposit.
- Record journal entries. Each transaction goes to the right account: a sale to revenue, rent to an expense, an equipment purchase to an asset, a loan received to a liability.
- Post to the general ledger. The ledger gives the running balance of every account and is what the statements are built from.
- Reconcile. Match the bank, credit card and loan balances to their statements, and match receivables and payables to customer and vendor records. This is where missing entries, duplicates and wrong amounts show up.
- Run the trial balance. Total debits must equal total credits. If they do not, find the double posting, missed entry or misclassification before going further.
- Post adjusting entries. Record accrued expenses (a bill for work already received but not yet invoiced), prepaid expenses used up in the period (a month of an annual insurance policy), depreciation, accrued income and inventory adjustments from a count or your inventory system.
Only once the adjusted trial balance is clean do you prepare the statements.
Profit and Loss (P&L) Statement Preparation
The P&L, also called the income statement, shows whether the business made money over a period: a month, a quarter or a year. It summarizes revenue, costs and expenses, and it is built top down, from the top line to the bottom line:
- Revenue. Total sales for the period, less returns, discounts and allowances, gives net revenue.
- Cost of goods sold (COGS). The direct cost of what was sold: product cost, inbound freight and, for a service business, the staff time that delivers the service. Items bought but not sold stay on the balance sheet as inventory.
- Gross profit. Net revenue minus COGS. A falling gross margin usually means rising product costs, heavier discounting or more returns.
- Operating expenses. The costs of running the business that are not tied to a single sale: marketing, salaries, rent, software, fulfillment, insurance and depreciation. These are often grouped as selling, general and administrative expenses.
- Operating income. Gross profit minus operating expenses. It shows whether the business model works before funding decisions and tax.
- Interest and other items. Interest on loans and one-off gains or losses sit below operating income so that periods can be compared on operations alone.
- Income tax and net income. What remains after tax is the bottom line, a profit if positive and a loss if negative.
Free guide
How to Read Your Financial Statements: A Monthly Guide for Small Business Owners
A monthly routine for reading your statements, with a worked example.
Balance Sheet Preparation: The Process
The balance sheet is a snapshot of the business on one date, usually the last day of the month or year. It follows one equation, which the SEC guide puts as assets equal liabilities plus shareholders’ equity:
Assets = Liabilities + Equity
Everything the business owns was paid for either with money it owes or with money the owners put in or left in the business.
Preparing the Assets Section
| Asset type | What it means | Examples | How to check it |
|---|---|---|---|
| Current assets | Cash or items that turn into cash within a year | Cash, accounts receivable, inventory, prepaid expenses | Match cash to bank statements, age receivables, count or pull inventory from your system, expense the used part of prepaids |
| Non-current assets | Used over several years | Equipment, computers, vehicles, trademarks, long-term investments | Record at cost, apply depreciation and amortization, remove assets no longer in use |
Preparing the Liabilities Section
| Liability type | What it means | Examples |
|---|---|---|
| Current liabilities | Due within a year | Supplier bills (accounts payable), accrued expenses, credit card balances, sales tax payable, the current portion of loans |
| Long-term liabilities | Due after a year | Bank loans, equipment financing |
Preparing the Equity Section
Equity is what belongs to the owners: capital they put in plus retained earnings, which is every past period’s net income less any distributions. This month’s net income from the P&L is added here, which is why the P&L comes first. If total assets do not equal total liabilities plus equity, something was missed in the close.
A worked example: one month for a consumer brand
The figures below are illustrative, for an online brand selling its own products, to show how the statements connect.
P&L for the month
| Line | Amount |
|---|---|
| Gross sales | $250,000 |
| Less returns and discounts | ($20,000) |
| Net revenue | $230,000 |
| Cost of goods sold | ($92,000) |
| Gross profit | $138,000 |
| Marketing | ($60,000) |
| Payroll | ($30,000) |
| Fulfillment and shipping | ($18,000) |
| Software, rent and other, including $1,000 depreciation | ($10,000) |
| Operating income | $20,000 |
| Interest | ($2,000) |
| Income tax | ($4,000) |
| Net income | $14,000 |
Balance sheet at month end
| Assets | Amount | Liabilities and equity | Amount |
|---|---|---|---|
| Cash | $120,000 | Accounts payable | $70,000 |
| Receivables (marketplace payouts due) | $15,000 | Accrued expenses | $20,000 |
| Inventory | $180,000 | Credit cards | $15,000 |
| Prepaid expenses | $10,000 | Long-term loan | $60,000 |
| Equipment, net | $25,000 | Owner’s capital | $100,000 |
| Retained earnings, including this month’s $14,000 | $85,000 | ||
| Total assets | $350,000 | Total liabilities and equity | $350,000 |
The P&L shows a $14,000 profit. The cash flow statement below shows why cash still fell.
Cash Flow Statement Preparation
The P&L records sales and expenses when they are earned or incurred, not when cash moves. A sale booked today may be paid out by a marketplace weeks later, and inventory bought for next season is paid for now but only expensed when it sells. As the SEC guide puts it, an income statement can tell you whether a company made a profit, while a cash flow statement tells you whether it generated cash.
The statement has three sections:
| Section | What it shows | Example items |
|---|---|---|
| Operating activities | Cash from the day-to-day business | Customer collections, supplier and payroll payments |
| Investing activities | Cash spent on or received from long-term assets | Buying equipment, selling an old asset |
| Financing activities | Cash from and to lenders and owners | Loans received or repaid, owner investment, distributions |
The simplest way to prepare it is the indirect method: start with net income, add back non-cash expenses such as depreciation, then adjust for changes in working capital. In the example, the month’s cash flow reads:
| Line | Amount |
|---|---|
| Net income | $14,000 |
| Add back depreciation | $1,000 |
| Inventory increased | ($30,000) |
| Payables increased | $12,000 |
| Receivables increased | ($5,000) |
| Cash from operating activities | ($8,000) |
| Equipment purchased | ($5,000) |
| Loan repaid | ($3,000) |
| Net change in cash | ($16,000) |
| Opening cash | $136,000 |
| Closing cash, matching the balance sheet | $120,000 |
A profitable month, and cash still fell by $16,000, because money went into inventory for the next season. That is the question the cash flow statement exists to answer.
Review, reconcile and report
Before the statements go to anyone, run a final review:
- Tie closing cash on the balance sheet and the cash flow statement to the bank.
- Compare each line to last month and to budget, and explain any large change.
- Check tax balances, loan balances and payroll liabilities against their statements.
- Confirm the statements follow your framework, which for most US private companies is US GAAP.
Then turn them into management reports: budget against actual, profitability by product or channel, and a cash forecast. Our guide to management reporting vs financial reporting explains how the two differ, and what a financial statement is covers the basics for anyone new to them.
The Best Practices to Follow
- Close on a calendar. Pick a close date, such as the tenth business day of the month, and hold to it.
- Reconcile monthly, not at year end. Bank, card, loan and marketplace payout accounts every month.
- Use one chart of accounts that matches how you manage the business, with COGS, fulfillment and marketing kept separate.
- Book payouts gross. Record marketplace and processor sales at the full amount, with fees and refunds as their own lines, so the P&L shows the real cost of each channel.
- Keep a close checklist so every adjustment is made the same way each month.
- Review cash weekly between closes, since cash problems move faster than monthly statements.
How Atidiv Could Guide You with Financial Statement Preparation
Our finance and accounting team provides outsourced reporting for the monthly close and produces income statements, balance sheets, cash flow reports, variance reports and management dashboards, along with board and lender reports. We support US GAAP and IFRS reporting, and our team works in QuickBooks, Xero, NetSuite, Sage and other accounting platforms, with our finance team in India.
If you want reliable statements every month without building the team in-house, see our financial reporting services, or start with our bookkeeping services if the records themselves need work first.

Free guide
How to Read Your Financial Statements: A Monthly Guide for Small Business Owners
A monthly routine for reading your statements, with a worked example.
Frequently asked questions
How do you prepare a P&L and balance sheet?
Close the books first: record and reconcile every transaction, run a trial balance and post adjusting entries. Prepare the P&L from net revenue down through COGS and operating expenses to net income. Then prepare the balance sheet, adding net income to retained earnings, and check that assets equal liabilities plus equity.
Which financial statement is prepared first?
The income statement (P&L) comes first, because its net income flows into retained earnings on the balance sheet. The balance sheet comes second, and the cash flow statement last, since it uses net income and the changes between balance sheets.
What is the first step in preparing financial statements?
Accurate bookkeeping. Every transaction must be recorded and the bank and card accounts reconciled before any statement is prepared, because every later step depends on those records.
Why does my business show a profit but still run short of cash?
Profit is recorded when a sale is made, not when the money arrives, and inventory is paid for before it is expensed. Slow payouts, inventory buys and loan repayments can all drain cash in a profitable month. The cash flow statement shows exactly where it went.
How often should financial statements be prepared?
Monthly for internal management, quarterly for performance reviews and lenders, and annually for tax and investors. Growing consumer brands benefit most from a monthly close, since inventory and marketing spend change quickly.
What balance sheet items do banks look at before approving a loan?
Most lenders look at cash, existing debt, total liabilities against assets, working capital and owner’s equity. They want to see that the business can service new debt and that the owners have capital in it.
Maximilian Straub is the Chief Operating Officer for Guild Capital and oversees all areas of the company's strategic operations and portfolio performance across the world. He is also a board member for Atidiv, supporting its growth initiatives. He served as the Chief Operating Officer and Chief Financial Officer for Spring Place and had previously spent 7 years advising clients in strategy, operational execution and organizational transformation while at McKinsey & Company.